SuperEx Educational Series: Understanding Why Can the Actual Execution Price Differ Even After a Stop-Loss or Conditional Order Is Triggered
#SuperEx #EducationalSeries
When traders encounter stop-loss slippage for the first time, they usually ask the same question:“I clearly set my stop price at 90. Why was the order filled at 88?”
The next round of suspicion often follows a familiar path: Did the system freeze? Did the platform secretly change the price? Or did the entire market somehow decide to target this one small position?
In most cases, the explanation is less dramatic.
A stop price or conditional trigger price only determines when an order begins entering the execution process. It is neither a reserved execution price nor a guarantee of the final fill price.
Between “the trigger condition is reached” and “the order is actually filled,” several steps still remain: price-source confirmation, order generation, risk checks, submission to the matching engine, finding counterparties, and filling across available price levels.
In a calm market, these steps appear almost simultaneous. During intense volatility, the gaps between them suddenly become visible.

The Trigger Price Is Not the Execution Price
A conditional order can be understood as a prewritten instruction:“If a specified price reaches 90, submit a sell order for me.”
Before the trigger occurs, the actual sell order may not yet exist in the order book. The system is simply monitoring the selected price source and waiting for the condition to be met.
A conditional order therefore contains at least two separate concepts:
- The trigger price determines when execution begins.
- The order type determines how the order behaves after activation.
This distinction may appear small, but it is the key to understanding execution-price differences.
If the trigger creates a market order, the system attempts to execute immediately against the prices available in the order book. The probability of execution is generally higher, but the final price may differ from the trigger price.
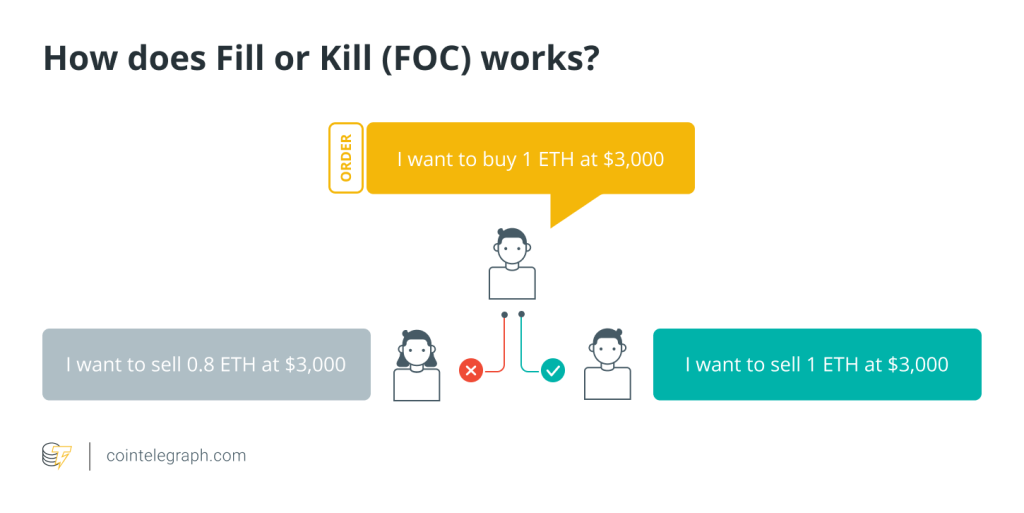
If the trigger creates a limit order, it will only execute at the specified price or better. The price boundary is clearer, but if the market moves beyond that limit too quickly, the order may be partially filled or not filled at all.
This creates a tradeoff that cannot be entirely eliminated:
- A stop-market order prioritizes exiting quickly but does not guarantee the price.
- A stop-limit order prioritizes a minimum acceptable price but does not guarantee an exit.
During gaps or insufficient liquidity, it is generally impossible to guarantee both immediate execution and a fixed execution price. Markets are not wish-granting machines. Selecting two preferences does not automatically produce a perfect third outcome.
Investor.gov similarly explains that a stop price is a trigger that turns a stop order into a market order. The final execution price may differ significantly because it depends on available liquidity. A stop-limit order can control the acceptable price but may remain unfilled. Investor.gov guidance on stop orders
Why Can the Market Change Before the Order Is Filled?
To understand the execution price, we first need to understand the order book.
An order book does not contain one single “current price.” It contains buy and sell orders at different prices and quantities. The latest price shown on the trading page is usually only the price of the most recent trade. It does not mean that enough liquidity is available at that exact level.
Suppose a stop order is triggered at 90, while the available bids are:
- 10 tokens at 89.8;
- 20 tokens at 89.3;
- 50 tokens at 88.0.
If the user needs to sell 60 tokens at market, the entire order cannot be filled at 89.8. It consumes liquidity across several levels, producing a volume-weighted average execution price.
The first 10 tokens fill at 89.8, the next 20 at 89.3, and the remaining 30 at 88.0. The average execution price is approximately 88.73.
The trigger was 90, the best bid was 89.8, yet the average fill was 88.73. Nobody altered the order. The order was simply larger than the liquidity available at the best price.
The larger the position and the thinner the order book, the greater the potential difference between trigger price and execution price.
In a highly liquid major trading pair, a small order may consume only one price level. In a thin market, even a modest order can sweep through several bid levels.
Extreme volatility magnifies the difference.
When major news, panic, or cascading liquidations hit the market, many stop orders may trigger around the same price. The nearest bids are quickly consumed by earlier orders, forcing later orders to execute against lower levels.
This is why slippage often becomes largest precisely when stop-loss protection is needed most.
Everyone is trying to leave through the same door. The door has not disappeared, but the exit is suddenly crowded. Traders further back in the queue may receive worse prices.
The difference becomes even larger when the market gaps.
For example, the last trade may occur at 90.2, while the next available bids are suddenly around 87. The condition is triggered as the price passes 90, but the first actual counterparties are already near 87. The system cannot execute at a price where no buyer exists.
The Price You See May Not Be the Price Your Order Monitors
Futures trading commonly involves a last traded price, mark price, and index price.
All three describe the market, but they serve different purposes and may temporarily diverge.
The last traded price is the price of the most recent transaction on the platform. It reacts quickly but can be moved by a large order or thin liquidity.
The mark price generally references an index, funding conditions, and a reasonable basis. It helps reduce the effect of short-lived abnormal trades on unrealized profit and loss or liquidation.
The index price is usually calculated from multiple spot markets or price sources and aims to reflect the broader external market.
If the user selects the mark price as the trigger source, the stop may not activate even when the last-price candlestick touches the stop level, as long as the mark price has not reached it.
Conversely, once the mark price reaches the condition, the resulting order still executes against the platform’s order book. The fill price therefore depends on available bids and asks, not on the mark price itself.
This can produce a result that looks confusing but is logically consistent:
- The mark price triggers the stop at 90.
- The last traded price is 89.6.
- The order’s average execution price is 88.9.
All three prices differ because they represent the trigger reference, the latest market trade, and the user’s actual fills.
When reviewing a conditional order, it is not enough to point at one candlestick and ask why the order did not fill there. First identify the trigger source, then examine the order book and trade details around the activation time.
A chart can show where the market traded. It does not necessarily show how much liquidity was available at that price.
What Else Can Happen Between Triggering and Execution?
Beyond order-book depth, conditional orders are also affected by timing and account status.
After the trigger condition is met, the system must detect the event, generate the order, check quantity and account conditions, and submit it to the matching queue. Modern matching systems are usually fast, but markets can move through several price levels in a very short time.
Queue position also matters.
Matching generally follows price priority and time priority. More competitive prices execute first, and earlier orders take priority at the same price. Even when many stop orders trigger at the same level, they cannot all occupy the same place in the queue.
Account conditions may also change before activation.
The user may manually reduce the position, transfer funds, remove margin, or have another strategy order execute first. Some conditional orders do not reserve the relevant funds or position before activation, so the system must check available quantity and margin again at the trigger time.
If the order exceeds the available position, margin is insufficient, or the market is paused or subject to price limits, the order may fail to submit, fill only partially, or remain open in the order book.
At that point, the question is no longer merely why the execution price differs. It is that triggering does not equal successful execution.
On-chain conditional orders introduce additional variables such as block confirmation, executor response time, gas pricing, and network congestion.
After the condition is met, an automated executor must submit a blockchain transaction. Before that transaction is included in a block, the AMM pool price may change and other transactions may alter its reserves. On-chain conditional orders can therefore also execute at a price different from the trigger level.
Complete Example: Stop at 90, Filled at 88.73
Suppose Alice holds 60 units of a long futures position opened at an average price of 100.
She creates a stop-loss condition:
- Trigger when the mark price reaches 90.
- After triggering, submit a market order to sell all 60 units.
The market suddenly falls. The mark price reaches 90, activating the conditional order. At that moment, the available bids are 10 units at 89.8, 20 units at 89.3, and 50 units at 88.0.
Alice’s market order enters the matching engine and consumes 60 units across those levels, producing an average execution price of 88.73.
This does not mean the stop-loss failed. It activated when the mark price reached 90 and helped Alice exit the market.
But a stop-loss controls when the exit process begins. It cannot create buyers around 90 when no such orders exist.
If Alice had instead used a stop-limit order with a trigger at 90 and a sell limit at 89.5, the outcome would differ.
The 10 units at 89.8 might fill, but bids at 89.3 and 88.0 are below her minimum acceptable price. The remaining 50 units would stay open, leaving Alice with most of the position. If the market continued falling, her loss could grow further.
The stop-market order exposes her to execution-price uncertainty. The stop-limit order exposes her to non-execution risk.
The choice is not about which button is more advanced. It is about which risk the trader chooses to control first.
How Can Conditional Orders Better Match a Trader’s Risk Objective?
First, confirm the trigger-price type.
The last price closely follows real-time trades on the platform. The mark price can reduce activation caused by short-lived abnormal trades. The index price follows a broader external market reference. No source is always best. The important thing is knowing which one has been selected.
Second, choose between market and limit execution according to the objective.
If the main goal is to reduce position risk quickly, market execution generally offers a higher probability of filling, but slippage must be expected. If execution below a certain price is unacceptable, a limit order can enforce that boundary, but it may not fill completely.
Third, examine order-book depth rather than only the latest price.
Users can compare their intended closing quantity with available volume across price levels and estimate the average execution price. The larger the position relative to market depth, the greater the slippage risk. Dividing a large position across several risk levels may also prevent the entire order from crowding into one trigger point.
Fourth, do not place the stop extremely close to the current price while expecting it to ignore all normal volatility.
A very tight stop is more likely to activate during short-term price noise. In leveraged and volatile markets, repeated activation can also increase fee and slippage costs. Stop distance should be considered together with asset volatility, position size, leverage, and risk tolerance.
Finally, a stop-loss is not the entirety of risk management.
If ordinary slippage on one exit would already be unbearable, the deeper problem may not be the stop setting. The position itself may be too large for the account to manage safely. A stop can help exit the market, but it cannot repair excessive leverage.
Taking SuperEx as an Example: How Should TP/SL Execution Be Understood?
Take SuperEx futures trading as an example. Users can set trigger conditions based on the latest market price, mark price, or index price. The preset order is sent to the market only after the selected price reaches the trigger level.
In other words, activation occurs first, while market submission and matching happen afterward. The steps are closely connected but are not the same action. SuperEx TP/SL guide
SuperEx also supports market and limit execution for take-profit and stop-loss orders. A market order seeks rapid execution against prices available at that moment, while a limit order waits for counterparties that satisfy the user’s price condition.
According to SuperEx’s documentation, market volatility, order-book depth, order size, price-time priority, and available margin can all affect whether an order fills, whether it fills completely, and what its final execution price will be. SuperEx conditional-order execution guide
The platform provides different risk-management tools through multiple trigger sources, order types, and risk prompts. These tools must still be understood within the market’s execution mechanics. A trigger price should not be treated as a guaranteed fill.
A more informed approach is to consider the trigger source, execution method, market depth, position size, and margin status when placing the order, instead of discovering afterward that “90 was only the start button.”
Conclusion
The actual execution price may differ after a stop-loss or conditional order is triggered because activation and execution are two separate stages.
The trigger price answers: “When should the order be submitted?”
The execution price answers: “At what prices are real counterparties willing to fill it after it reaches the market?”
The price source determines when the condition is met. The order type defines execution boundaries. Order-book depth determines how much can fill. Volatility and queue position determine which prices are actually reached.
A market order offers a higher probability of exiting but carries slippage risk. A limit order controls the worst acceptable price but carries non-execution risk.
A stop-loss does not provide a price guarantee. It provides an automated response rule.
It can help execute a risk plan before emotion takes control, but it cannot freeze the market, create liquidity, or require other traders to fill an order at the number written on the screen.
In plain English, the stop price sounds the alarm. The order book determines which exit you use and how crowded that exit is.
About SuperEx
SuperEx is committed to building a Web3-centered digital asset ecosystem, offering global users crypto trading, Web3 wallet, DAO, earning, and educational services. Through trading infrastructure, risk-management tools, continuous market monitoring, and user education, SuperEx aims to help users understand trading mechanisms and manage digital asset risk more responsibly.
Click to register SuperEx
Click to download the SuperEx APP
Click to enter SuperEx CMC
Click to enter SuperEx DAO Academy — Space
Responses