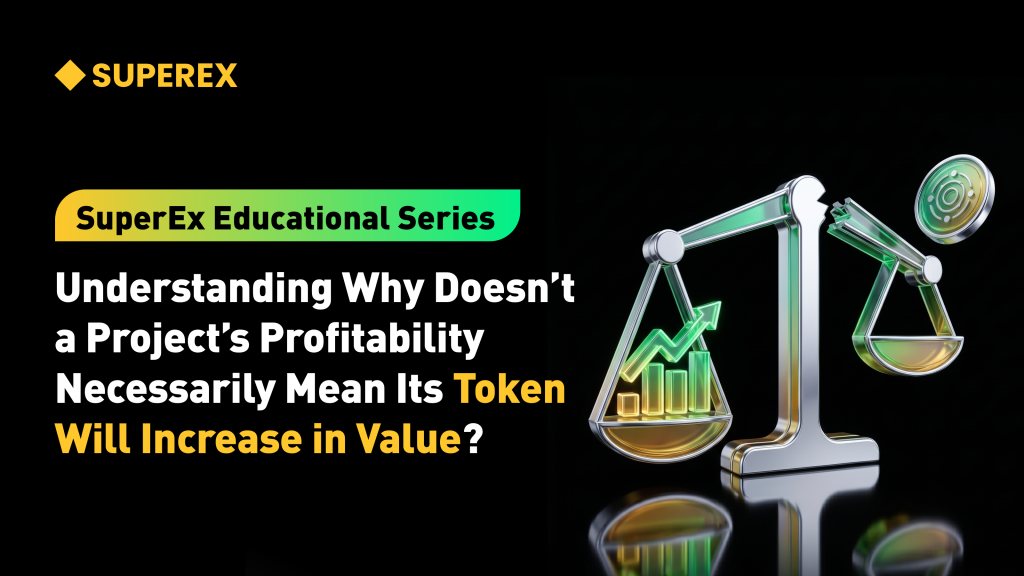
SuperEx Educational Series: Understanding Why Doesn’t a Project’s Profitability Necessarily Mean Its Token Will Increase in Value
#SuperEx #EducationalSeries #Token
There is a very convenient line of reasoning in the crypto market:The project is profitable, so its fundamentals must be strong. Strong fundamentals should naturally make the token rise.
It sounds perfectly reasonable and even resembles traditional financial analysis. Then reality arrives and sends the token price sharply lower.
Monthly project revenue reaches a record high while the token falls 30%. Protocol volume keeps growing while the token trades sideways. The team announces profitability just as a large investor unlock begins.
What went wrong?
The problem is usually not that the project failed to make money. It is that there is no automatic conveyor belt carrying project profits into token value.
A company’s shares usually represent an economic claim on that company. Higher profits may support dividends, buybacks, or expectations of future cash flow.
A token does not necessarily represent equity in the project company, nor does it automatically carry rights to profit distribution. It may function as a governance tool, access credential, incentive asset, or simply a tradable symbol associated with the ecosystem.
A project making money proves only that a particular business entity earned revenue. Whether the token gains value depends on whether that revenue creates token demand, reduces token supply, or gives holders enforceable economic rights.
Put simply, a project may have an excellent financial statement while its token never receives the paycheck.

First Separate the Company, the Protocol, and the Token
Many crypto projects contain three different entities.
The first is the project company or development team.
It may develop software, operate websites, sell enterprise services, provide APIs, manage the brand, and earn revenue through subscriptions, technical services, advertising, custody, or institutional partnerships.
The second is the on-chain protocol.
The protocol consists of smart contracts and public rules. Users interact with it through trading, lending, staking, and other activities. It may generate trading fees, borrowing interest, liquidation revenue, or registration fees.
The third is the token itself.
It may be used to pay gas, participate in governance, receive discounts, provide collateral, secure the network through staking, or incentivize users and developers.
These three entities may be tightly connected, or they may simply share the same brand name.
Suppose a project company earns 10 million dollars annually by selling data APIs to institutions. Customers pay in dollars, revenue enters the company’s bank account, and profits belong to company shareholders.
If the token is not required to pay for the API, carries no profit-distribution rights, and the company does not use profits to buy back or burn tokens, then the connection between company revenue and token value is primarily branding rather than economic transmission.
Users may still buy the token because they believe in the company, but that is a market expectation rather than a contractual guarantee.
Protocol revenue does not necessarily belong to token holders either.
In a DEX, trading fees may go mostly or entirely to liquidity providers. On a blockchain network, fees may be paid to validators or burned. In a lending protocol, most interest may go to suppliers while only a small portion enters protocol reserves.
When seeing that a protocol generated 100 million dollars in annual fees, the first response should not be to immediately value its token. The first questions should be:
- Who paid these fees?
- Who ultimately received them?
- Do token holders receive any portion?
- If not, is there a clear, credible, and enforceable mechanism for future value transmission?
Total fees, protocol revenue, company profit, and token-holder returns are four different figures.
Placing them on the same promotional graphic does not make them economically identical.
How Can Profit Actually Flow Into a Token?
For project profitability to influence token value, there must be a bridge between the two.
The bridge can take several forms, but all must answer one question: why should stronger project performance make the market more willing to buy or hold the token?
The First Bridge Is Required Usage
If users must use the token to access protocol services, business growth may directly increase demand for it.
For example, a blockchain may require its native token for gas. As network activity grows, more users need the token to execute transactions.
Ethereum gas is paid in ETH. The base fee is burned, while validators receive part of the economic reward. This creates a protocol-level connection between network usage, ETH demand, and supply changes. Ethereum Gas and Fees
There is a major difference between “the token can be used” and “the token must be used.”
If users can perform the same action with stablecoins, fiat, or other tokens, and the project token offers no meaningful advantage, its utility may not produce durable demand.
More importantly, usage demand is not necessarily holding demand.
If users buy the token immediately before payment and service providers sell it immediately afterward, turnover remains high and business growth may not create long-term capital retention.
The Second Bridge Is Fee Distribution
A protocol may distribute part of its fees to stakers, governance participants, or other token holders.
This resembles conventional cash flow more closely because token holders receive part of protocol activity under defined rules.
Several details still matter.
- Is fee distribution already active, or does it exist only as a future plan in the whitepaper?
- What asset is distributed? Stablecoins, major assets, or newly issued project tokens?
- Must the token be locked, and what price or liquidity risks arise during that period?
- Can the distribution ratio be changed at any time by the team or governance?
If the yield comes entirely from newly issued tokens, it resembles an inflation subsidy rather than business profit.
The Third Bridge Is Buybacks and Burns
A project or protocol may use part of its revenue to buy tokens from the market and then hold, burn, or redistribute them.
Buybacks create purchasing demand, while burns reduce circulating or total supply. In theory, these mechanisms can transmit business revenue into token supply and demand.
Announcing a buyback does not automatically create value capture.
Users should examine whether buybacks come from genuine operating revenue or treasury funds, whether they are executed consistently, whether tokens are actually burned, and whether larger team unlocks or ecosystem emissions occur at the same time.
If a project buys back one million tokens per month while releasing ten million, new supply may still overwhelm buyback demand.
Ethereum’s fee burn provides a relatively clear protocol-level example. Network activity produces base fees that are permanently removed from supply, while new ETH is also issued as validator rewards. The resulting supply change depends on the balance between issuance and burn, not on burn alone. Ethereum ETH Supply and Issuance
The Fourth Bridge Is Collateral, Staking, and Security Demand
Some tokens must be locked to operate validators, provide oracle services, obtain protocol privileges, or supply economic security.
As protocol scale grows, the amount of economic security required may also rise, potentially increasing demand to hold the token.
This is not an automatic value guarantee either.
If staking rewards come primarily from high emissions, stakers receive more tokens while non-stakers are diluted. If service demand remains weak, new tokens may continue entering the market.
The important question is not how many “utilities” a token claims to have, but whether those utilities create durable demand that cannot easily be replaced.
Even When Value Is Transmitted, Supply Can Cancel It Out
A token’s price is formed through marginal buying and selling, not through the project’s annual report.
Improving profitability may create additional demand. But if even more tokens enter circulation during the same period, price may still decline.
New supply commonly comes from team unlocks, early-investor vesting, ecosystem incentives, staking rewards, community airdrops, and treasury spending.
These tokens may not be sold immediately, but they increase potential supply.
This is where circulating market capitalization and fully diluted valuation must be separated.
Suppose a token trades at 2 USDT with 100 million tokens circulating. Its circulating market capitalization is 200 million USDT.
If total supply is one billion tokens, its fully diluted valuation is 2 billion USDT.
If another 900 million tokens are scheduled to enter circulation over time, existing holders face a very long queue of future supply.
A project earning 5 million dollars annually does not automatically make a 2 billion dollar fully diluted valuation inexpensive.
Even if all profit could flow to the token, the market may already have priced in much stronger future growth.
This is why a good project is not automatically a good price.
Revenue rising from 1 million to 10 million dollars looks impressive. But if the token was already valued as though future revenue would reach 100 million, the actual result may disappoint the market.
Markets trade changes in expectations, not the headline alone.
Token supply and demand can be considered through a simple framework:Net token demand is roughly the demand from usage, staking, buybacks, and long-term holding, minus unlocks, emissions, reward selling, and exits by early holders.
Project profit affects only part of this demand. It does not automatically absorb all new supply.
Why Can a Profitable Project’s Token Still Fall?
Suppose Project A operates a blockchain data platform.
The company sells APIs, risk data, and custom reports to institutional clients. Annual revenue reaches 30 million dollars, and net profit after staffing, infrastructure, and operating costs is 8 million dollars.
From a corporate perspective, this is a healthy business.
Project A also issues Token A with a total supply of one billion tokens. One hundred million are circulating at a price of 2 USDT.
Token A provides governance voting and a 10% service discount, but institutional clients continue paying mostly in dollars. Company profits are not distributed to token holders.
Over the next year, 200 million tokens allocated to the team, investors, and ecosystem funds unlock.
Some are used to pay employees and partners, while early investors sell part of their holdings. Meanwhile, only a small number of users buy the token for the service discount.
The result appears contradictory but is economically coherent:
- The company remains profitable;
- Protocol users continue to grow;
- The token’s market supply increases rapidly;
- Token demand does not grow at the same rate;
- The price therefore falls from 2 USDT to 1.2 USDT.
The company’s profit did not disappear. It belonged to company shareholders and did not automatically become token demand.
Now suppose the project announces that 10% of annual profit, or 800,000 dollars, will be used for token buybacks.
This creates a genuine value-transmission mechanism.
But if tens of millions of dollars worth of tokens unlock during the same period, an 800,000-dollar buyback may remain too small to offset potential selling pressure.
The correct question is not merely whether the project conducts buybacks, but how large those buybacks are relative to new supply.
Profitability is a positive fundamental factor, but it must pass through token mechanics and market supply-demand before affecting price.
What Should We Examine to Determine Whether a Token Captures Project Value?
When analyzing a token, it is useful to temporarily set aside promotional language about “ecosystem empowerment.”
Start by tracing the actual flow of money.
- What asset do users pay? Does the money enter a company account, a smart contract, or liquidity providers’ wallets?
- How much remains after paying validators, liquidity providers, and user incentives?
- Does the remaining revenue enter a transparent treasury, and who controls it?
- Does the token receive fee distributions, buybacks, burns, staking demand, or payment demand?
- Are these mechanisms active, or do they depend on a future governance vote?
Then examine supply.
- What portion of total supply is circulating?
- How much unlocks over the next twelve months?
- What were the acquisition costs for team members and investors?
- How many tokens are emitted as rewards each day?
Finally, examine valuation and expectations.
Even if the token genuinely captures cash flow, its current market capitalization, fully diluted valuation, revenue growth, and mechanism risks still matter.
A revenue-capturing token may still be overpriced. A token with no current revenue may still rise because of market expectations.
The former is not guaranteed to appreciate, while the latter does not imply sustainable growth.
SuperEx Example: Platform Screening Cannot Replace Token Value Analysis
Using SuperEx as an example, core launch channels such as Super Start do not focus only on whether a project has a product or revenue. The platform also reviews project background, value proposition, tokenomics, initial circulation, funding capacity, subscription rules, and risk disclosure.
Project profitability may indicate that the business has some ability to survive. It cannot by itself prove that the token is fairly valued.
Token-structure review must therefore examine whether the token has genuine utility, whether team and investor allocations are excessive, whether unlocks may pressure the market, whether initial circulation is unusually low, and whether the project accepts continuing responsibility after launch.
SuperEx’s risk-control process does not end when trading opens. The platform continues monitoring liquidity, trading activity, information accuracy, and emerging risks, with risk notices, service restrictions, or market adjustments available under platform rules. SuperEx Project Launch and Screening Overview
Strict screening still does not guarantee price appreciation.
A platform can review information, establish eligibility standards, monitor abnormal behavior, and improve disclosure. It cannot determine on behalf of the market what a token should be worth.
Particularly in open environments such as the SuperEx Free Market, users need to evaluate token contracts, liquidity, unlock schedules, and value-capture mechanisms themselves. SuperEx’s public rules also warn that Free Market tokens may involve volatility, smart-contract risks, and potential asset loss. SuperEx Free Market FAQ
Platform screening can reduce information asymmetry. Token analysis determines whether users understand what they are actually buying.
Conclusion
There is no straight line between project profitability and token appreciation.
A project company may be profitable while the token has no claim on those profits. A protocol may generate substantial fees while most of them go to validators, liquidity providers, or other participants. A token may have utility without creating lasting holding demand.
Mechanisms that can transmit project performance into token value include required payment demand, fee distribution, revenue-funded buybacks, supply burns, staking security, and difficult-to-replace protocol rights.
Even when such mechanisms exist, the token still faces unlocks, emissions, reward selling, early-investor exits, weak liquidity, and excessive valuation.
When a project announces profitability, do not ask only how much it earned.
Continue asking:
- Did the company earn the money, or did the protocol?
- Where did the revenue ultimately go?
- Does the token carry enforceable economic rights?
- How much new supply is coming?
- How much future growth is already priced in?
- Profit is a result achieved by the business. Token price is the market’s assessment of future supply and demand.
They can be related, but they are never automatically linked.
References
Ethereum: ETH Supply and Issuance
EIP-1559: Ethereum Fee Market Change
SuperEx: Why Exchanges Participate in Token Launches
About SuperEx
As the world’s first Web3-powered cryptocurrency exchange, SuperEx remains committed to building the Web3 ecosystem through products and services including SuperEx DAO, SuperEx Web3 Wallet, Super Start, SuperEx P2P, SuperEx Stock Markets, SuperEx Copy Trading, SuperEx Earn, and SuperEx DAO Academy.
Today, SuperEx serves more than 10 million users across 166 countries and regions and supports spot and futures trading for over 1,000 crypto assets.
Click to register SuperEx
Click to download the SuperEx APP
Click to enter SuperEx CMC
Click to enter SuperEx DAO Academy — Space
Responses